Most trusted prop firm criteria and how to score one yourself
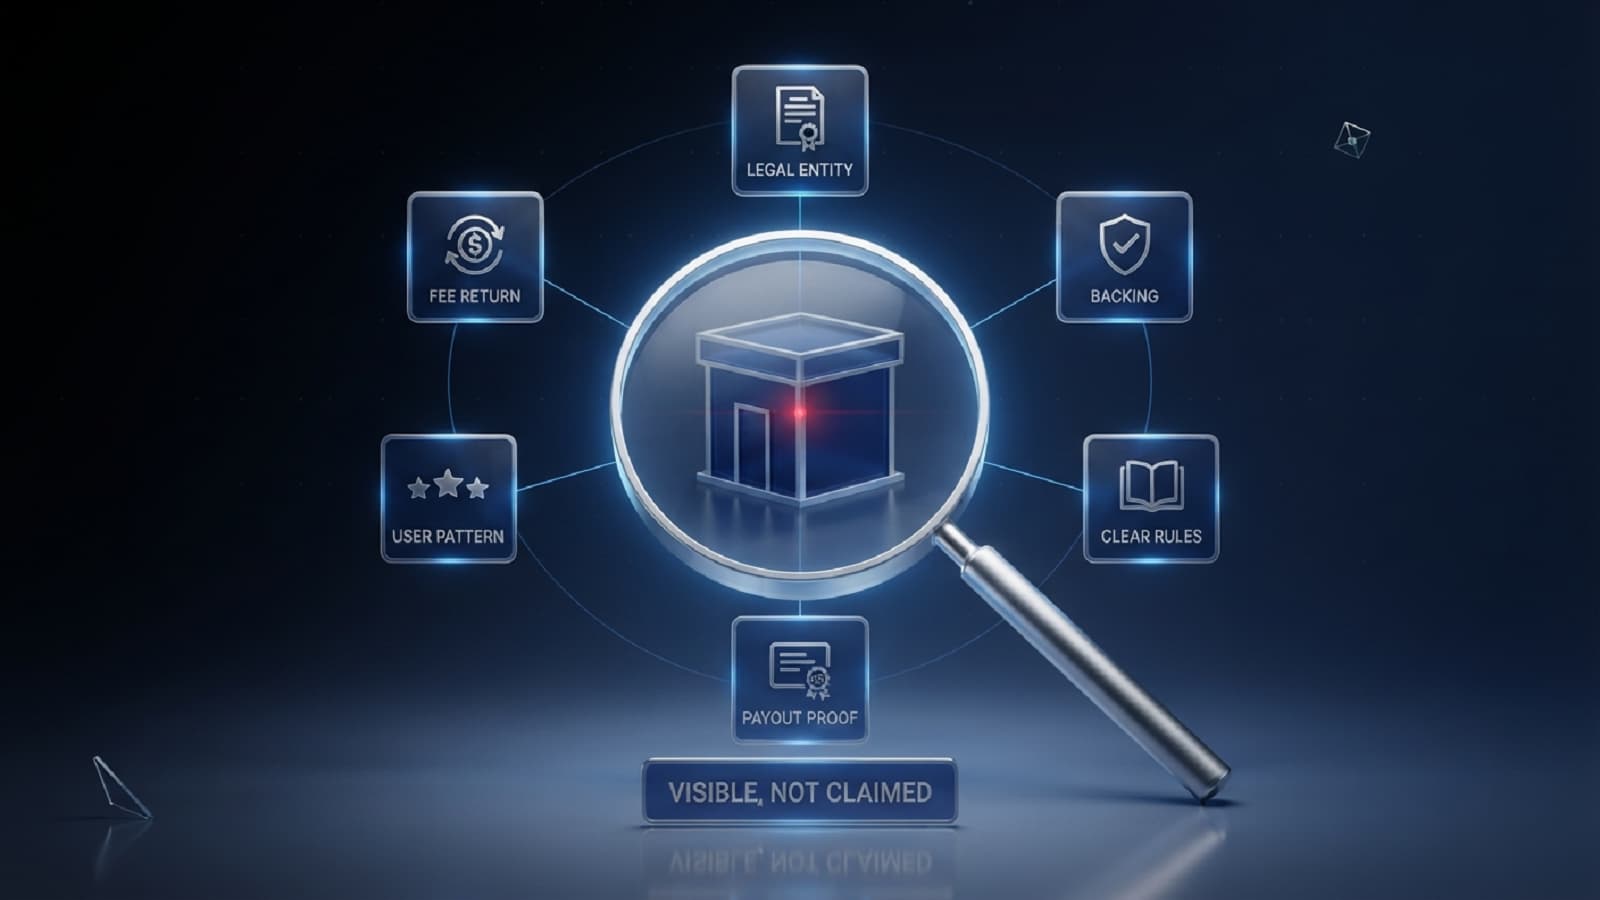
There is no register of the most trusted prop firm in this industry, so you answer the question by scoring, never by ranking. You can check five things before you pay anything: who is behind the brand, whether the company publishes its rules in advance, whether the payout process is dated and not merely described as fast, whether the drawdown model is static or trailing, and what happens to your money if you lose the account. This guide turns those five into a scorecard you can apply to any company, and then answers all five for NextGen Funding, which is backed by Errante.
Why the most trusted label has to be scored, never looked up
No supervisory authority publishes a trust ranking for evaluation firms, and no company is in a position to certify itself as the most reliable one. What does exist is a set of things a company either states in public or does not.
Here is the distinction that matters. Firms that publish a specific number for every stage have committed to something you can hold them to. Firms that only use adjectives have committed to nothing. Score on the presence of numbers, never on the strength of the language.
Criterion one: who is behind the brand
Evaluation firms generally fall outside the framework written for brokers, because they hold no client deposits. That is not a flaw in itself, but it makes the structure behind the brand the single most important thing to check.
Any company that is only a website can withdraw access at any point, with no institution behind it. Backing from a regulated broker means a supervised institution is behind the business, even though the evaluation itself is not a regulated product.
NextGen Funding is backed by Errante, a broker licensed by CySEC and the FSA Seychelles. NG Funding Services Ltd, a registered company with an office at 30 Karpenisiou, 1077 Nicosia, Cyprus, handles the payments, so there is an address you can look up. Those are checkable facts, which means you can verify them without trusting anyone.
What to ask
Which entity processes the payments, where is it registered, and which regulated institution is behind the brand. If none of those has a specific answer, that is your score for this criterion.
Criterion two: are the rules published before you pay
Problems in this industry do not always start with a refusal to pay. They can start with a rulebook loose enough that a firm can apply a clause after the fact, once a trader is in profit.
Trustworthy firms state the profit target, the maximum drawdown, the daily loss limit and the minimum trading days for each prop firm challenge before purchase, and do not change them partway through.
| Criterion | Standard | Rapid | Ace |
|---|---|---|---|
| Stages | 2 | 2 | 1 |
| Profit target | 10% and 5% | 8% and 5% | 10% |
| Maximum drawdown | 10% | 8% | 6% |
| Daily loss limit | 5% | 5% | 3% |
| Minimum trading days | 3 | 0 | 3 |
| Evaluation period | Unlimited | Unlimited | Unlimited |
| News trading | Phase 1 and Phase 2 only | Not allowed | Not allowed |
Standard and Rapid are each a 2-step challenge, and Ace is a 1-step challenge. Tables like this, available before purchase, are what this criterion tests for. For example, on a $100,000 Standard account the table means a $10,000 target in stage one, a breach level of $90,000 for the maximum drawdown and a $5,000 daily limit, all known before you pay.
Criterion three: is the payout process dated, and not just fast
This is where the phrase “best paying prop firms” usually gets used loosely. Payment speed is three numbers in sequence, and a firm that publishes only the last one has told you the least useful part.
- When the first withdrawal opens. Here that is 14 calendar days after your first trade on the funded account, with at least $100 in accumulated profit and the profit distribution rule satisfied, and each withdrawal must be at least $50.
- The interval afterwards. After that first withdrawal, every 7 calendar days, which in normal conditions means three or four withdrawals a month.
- The processing window and where it starts. 24 to 48 hours from when you submit the request, with the review inside that window.
A firm that answers all three with numbers has made a commitment, which means a trader can hold it to a date. One that says only “fast payouts” has given you nothing to hold it to.
The fee refund is part of this criterion
Your evaluation fee at NextGen Funding is refundable and comes back with your first withdrawal. NextGen Funding states its condition openly too. Lose the account before that first withdrawal and you get neither the accumulated profit nor the fee. For example, $3,000 of profit on the books becomes nothing. Publishing the caveat alongside the benefit scores better on this criterion than publishing only the benefit.
Criterion four: is the drawdown model static or trailing
Many traders discover this criterion too late, and it can change the difficulty of an evaluation more than the profit target does.
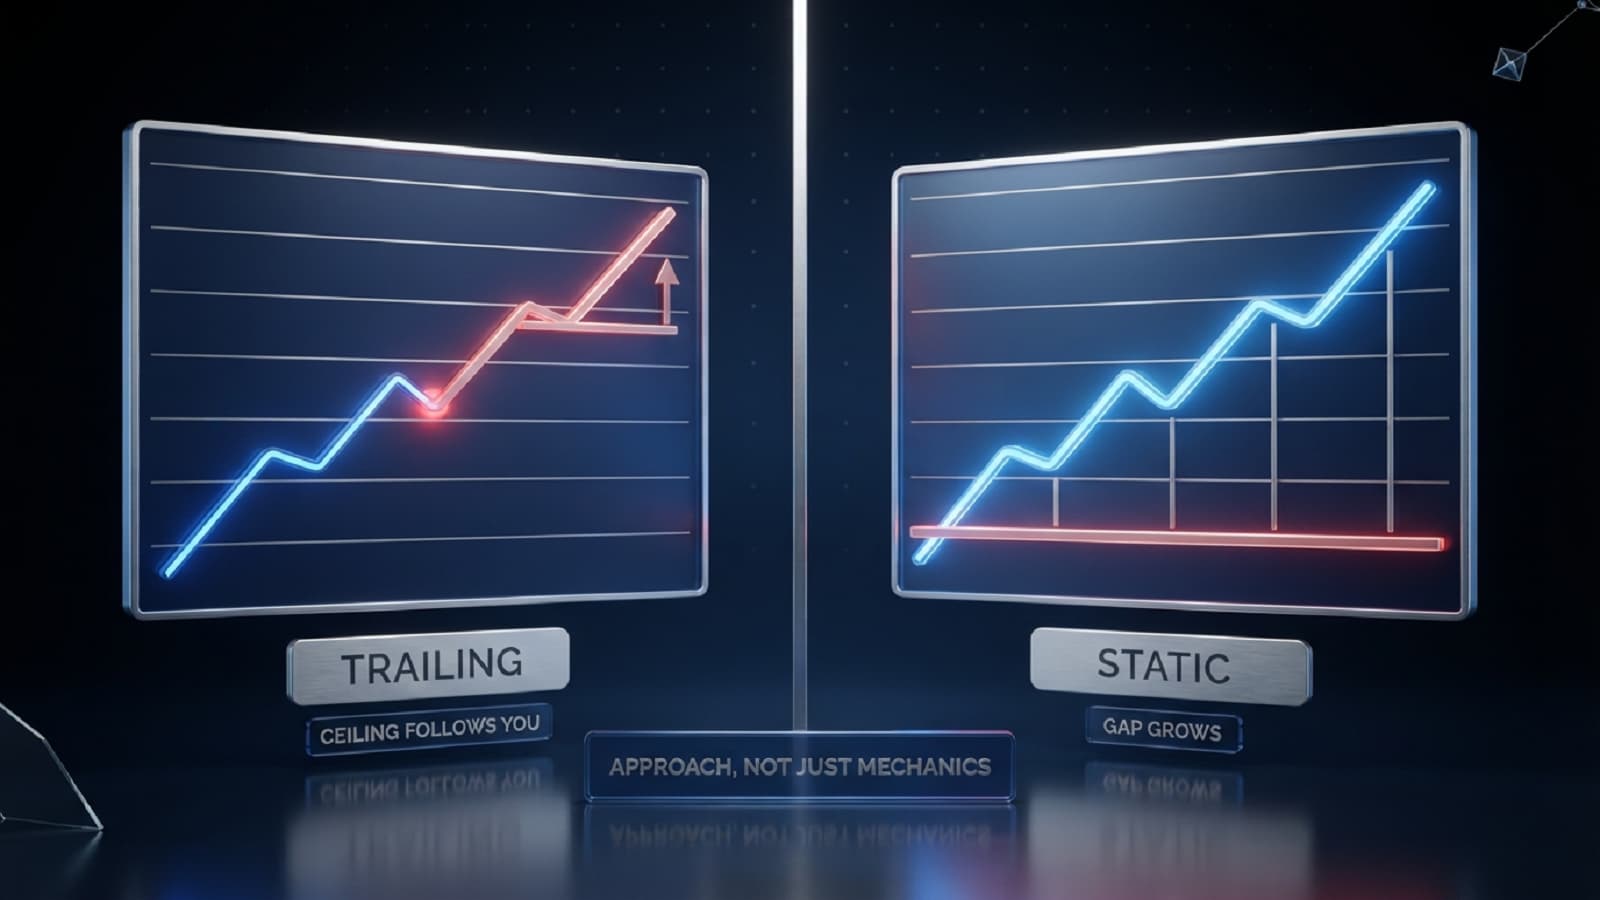
In a trailing model, which some other firms use, the breach level follows the account’s highest point. On a $10,000 account with a $1,000 trailing limit, the breach level starts at $9,000. If an open trade lifts equity to $10,500, the breach level rises to $9,500 and stays there, even if that trade then turns around. Say it falls back to $10,000: your equity is back where it started, but only $500 of room is left instead of $1,000. In a static model the breach level is set once from the initial balance and stays there, so profit increases your distance from it.
NextGen Funding uses the static model on both the evaluation and the simulated funded account. The full statement matters here, though, and a firm worth trusting gives you the full statement: the level of both limits comes from the account balance, with the daily loss limit set each day at 5 PM Eastern time from the previous day’s closing balance, but what triggers them is your account equity. A floating loss on an open position counts, and the system does not wait for the trade to close.
Why the complete version is itself a trust signal
That half sentence, our model is balance based, is technically true and leaves a trader believing they are safe while a position remains open. Publishing only that half is choosing the flattering half. Look for the second half.
Criterion five: what forfeits your money
Every firm has clauses that end an account. The question is whether they are visible before you pay.
Conditions here are stated: breaching the maximum drawdown or the daily loss limit ends the account, and an account with no 0.01 lot trade in any 90 day period becomes inactive, which forfeits the entry fee, the accumulated profit and any pending withdrawal. For example, a trader who last traded on 3 March has until 1 June to place the next trade. On Rapid, on Ace and on every funded account, from two minutes before to two minutes after a high impact release no opening or closing of trades is allowed, and that includes a stop loss or take profit being triggered; breaking that rule also ends the account.
Prohibited methods appear on a list too, including arbitrage in any form, high frequency trading, tick scalping, gap trading, passing a challenge with a single high-risk trade, copying trades from other traders and account sharing. You can still copy trades between your own accounts.
Publishing a list of ways to lose the account is a better signal than publishing none. Clauses you cannot find before paying are the ones that get applied afterwards.
A scorecard you can apply to any firm
| Criterion | What to look for | A weak answer |
|---|---|---|
| Backing | A named regulated institution and a registered payment entity | Only a brand and a website |
| Rules | Targets, drawdown and daily limit published before purchase | Rules spread across pages or stated vaguely |
| Payouts | Three dates: first withdrawal, interval, processing window | One speed claim with no dates |
| Drawdown model | Static or trailing, stated in full including the trigger | Half a sentence, or no statement at all |
| Forfeit clauses | A published list of what ends the account | Discovered only after a problem |
Score each one before you pay. Four clear answers and one vague one is a very different proposition from five vague ones.
Two things a trustworthy firm will not claim
Two claims should lower a company’s score instead of raising it.
First, being funded without an evaluation. A funded account here comes only after passing one of the three evaluations, and you are never funded instantly. There is no route that skips it.
Second, any promise about your results. No firm can promise you will pass or that you will earn a particular figure, because that depends on your strategy, your risk management and market conditions. What gets fixed in advance is the terms, not the outcome.
What consistency is worth over time
One last thing worth checking is whether the company has a defined plan for a trader who succeeds, instead of treating the first payout as the end of the relationship.
Here that is the scaling plan. In each 4 month cycle, at least 10% net profit (at least 2.5% per month) plus at least one completed withdrawal adds 25% of the initial balance, up to $1,000,000. Growth is linear and never compounding, and each step is the same size. Scaled-up accounts run at a 90% profit split. All trading runs on MetaTrader 5 (MT5).
Frequently asked questions
Which is the most trusted prop firm?
No authority publishes a trust ranking, and you answer the question by scoring instead of by looking up a list. Check five things before paying: the institution behind the brand, whether the company publishes its rules in advance, whether the company states its payout process as dates, whether the drawdown model is static or trailing, and what forfeits your money.
How can I tell if a prop firm is reliable before paying?
Look for numbers and not adjectives. A company that publishes a specific figure for every stage has committed to something you can hold it to. One that only uses descriptive language has committed to nothing.
Are prop firms regulated?
Generally not the way a broker is, because they hold no client deposits, and the evaluation itself is not a regulated product. That is why the structure behind the brand matters more than the absence of a broker licence.
Who is behind NextGen Funding?
Errante, a broker licensed by CySEC and the FSA Seychelles. NG Funding Services Ltd, a registered company with an office at 30 Karpenisiou, 1077 Nicosia, Cyprus, handles the payments.
What does “best paying prop firm” actually mean?
It should mean three published numbers instead of one: when the first withdrawal opens, how often you can withdraw after that, and the processing window and where it starts.
What are those three numbers at NextGen Funding?
14 calendar days from your first trade on the funded account to the first withdrawal, then a withdrawal every 7 calendar days, and processing within 24 to 48 hours of submitting the request.
Is the evaluation fee refundable?
Yes, with your first withdrawal. If the account is lost before that first withdrawal, you receive neither the accumulated profit nor the fee.
What is the difference between static and trailing drawdown?
A trailing breach level follows the account’s highest point: on a $10,000 account with a $1,000 trailing limit, an open trade that lifts equity to $10,500 raises it from $9,000 to $9,500. A static breach level is calculated once from the initial balance and stays there, so profit increases your distance from it.
Which model does NextGen Funding use?
Static, on both the evaluation and the funded account. The level is calculated from the account balance, but what triggers it is your account equity, and a floating loss on an open position counts.
Why is the full drawdown statement a trust signal?
Because the half sentence “our model is balance based” is true but leaves a trader believing they are safe while a position stays open. A firm publishing only that half has chosen the more flattering reading.
What can cause me to lose the account?
Breaching the maximum drawdown or the daily loss limit, opening or closing a trade inside the news window on an account where news trading is not allowed, using a prohibited method, and inactivity: no 0.01 lot trade in any 90 day period makes the account inactive, forfeiting the entry fee, accumulated profit and any pending withdrawal.
Which trading methods are prohibited?
Arbitrage in any form, high frequency trading, tick scalping, gap trading, passing a challenge with a single high-risk trade, copying trades from other traders and account sharing. You can still copy trades between your own accounts. Even a list of ways to lose is a better signal than no list.
Should I trust a firm offering funding without an evaluation?
Treat it as a reason for caution. At NextGen Funding a funded account comes only after passing one of the three evaluations, and you are never funded instantly.
Can any firm promise I will pass or earn a set amount?
No, and a specific promise should lower your score for that company. Results depend on strategy, risk management and market conditions. What can be fixed in advance is the terms, not the outcome.
What are the rules of each evaluation?
Standard: 10% and 5% targets, 10% maximum drawdown, 5% daily limit, 3 minimum trading days, news trading allowed in Phase 1 and Phase 2 only. Rapid: 8% and 5%, 8% drawdown, 5% daily limit, no minimum days, news not allowed. Ace: 10% in one stage, 6% drawdown, 3% daily limit, 3 minimum days, news not allowed.
Is there a deadline on the evaluations?
No. All three run with an unlimited period. Two timing conditions apply: a minimum of 3 trading days on Standard and Ace, and the 90 day activity rule on every account.
Does the firm have a plan for traders who succeed?
Yes, the scaling plan. In each 4 month cycle, at least 10% net profit (at least 2.5% per month) plus at least one completed withdrawal adds 25% of the initial balance, up to $1,000,000, and scaled-up accounts run at a 90% split.
Am I trading real money?
No. Every account, evaluation and funded alike, is a demo account with fictitious funds and all trading takes place in a simulated environment. Only the profit you withdraw is real.
All accounts we provide to our clients are demo accounts with fictitious funds and any trading is in a simulated environment only.